Gold Open Interest: Follow the Contract Ledger Before Reading Sentiment
Reconcile opening and closing futures transactions, distinguish open interest from volume and avoid treating every increase as directional buying.
An outstanding contract has two sides but one count
Open interest counts outstanding contracts under the reporting convention, not the number of bullish opinions or the total of long and short sides added together. Each outstanding futures contract connects a long and a short. When analyzing gold, identify the contract month, exchange, report date and whether figures are preliminary or final. Aggregating maturities answers a different question from following one contract. A large number does not directly measure money committed at the full contract notional, because futures collateral and outstanding exposure are different quantities. Begin with the accounting before attaching a story about participation.
Distinguish the three transaction pairings
If a new long trades with a new short, one new contract is created and open interest rises by one. If an existing long closes against an existing short that is also closing, open interest falls by one. If one participant opens while the counterparty closes, ownership of an outstanding side changes and open interest is unchanged. Every pairing can add traded volume. A tape showing a purchase does not reveal the full opening-versus-closing classification by itself. Preserve both sides of the transaction in a teaching ledger so the same traded contract is not counted twice as two new outstanding contracts.
Calculate a simple daily reconciliation
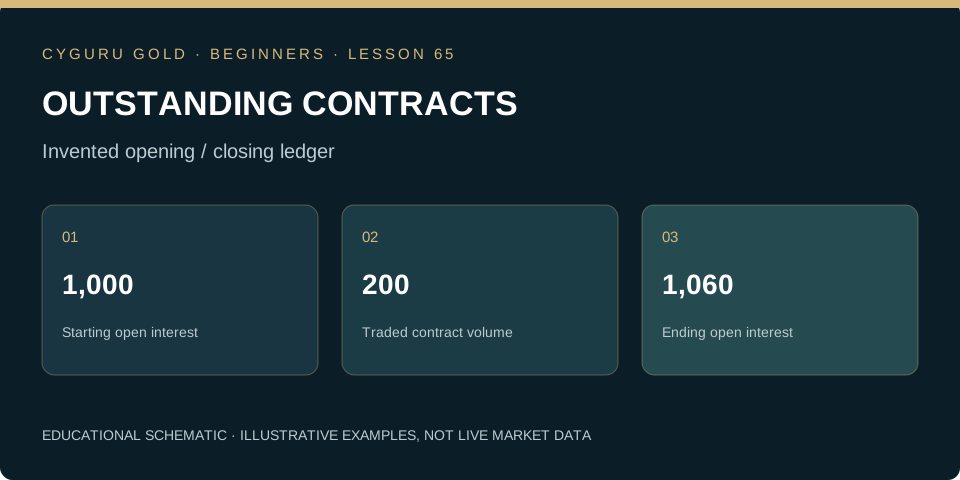
Start with an invented open interest of 1,000 contracts. During the day, 100 contracts trade between two opening sides, 40 between two closing sides and 60 between one opening and one closing side. These simplified transactions create volume of 200 contracts and a net open-interest change of +60. Ending open interest is 1,060. The figures do not disclose whether the opening longs were speculators or hedgers, nor whether their motivations were bullish. They demonstrate that a substantial volume number can coexist with a much smaller change in outstanding contracts. Treat the example as contract accounting rather than a sentiment model.
| Transaction pairing | Volume | OI change |
|---|---|---|
| Both open | 100 | +100 |
| Both close | 40 | −40 |
| One opens; one closes | 60 | 0 |
| Daily total | 200 | +60 |
| Starting / ending OI | 1,000 / 1,060 | One count per contract |
Separate a maturity roll from new aggregate exposure
As expiry approaches, participants may close a nearby contract and establish exposure in a later month. Nearby open interest can fall while deferred open interest rises, even when the broad economic exposure remains similar. Compare maturity-level changes and the provider’s aggregate series before interpreting one month’s decline as abandonment of gold. Delivery and final settlement can also change outstanding contracts under exchange procedures. A continuous chart does not automatically provide an equally continuous open-interest definition. Record the exact source and the time at which the daily data became available before using it in an intraday historical rule.
Do not turn a descriptive association into a cause
Rising price and rising open interest can be described together, but the combination does not prove which participant is informed or that the trend must continue. Both new long and new short exposure exist in the newly created contracts. Price can move with little outstanding-contract change if positions transfer rapidly. Report the observed price interval and publication timing, then distinguish the observation from a proposed trading hypothesis. The COT report provides categorized positioning on a different schedule and methodology; it is not a same-instant explanation of every daily change. Avoid importing unavailable future classifications into the decision record.
Practice task: build a balanced contract ledger
Reproduce the 1,060 ending open interest and 200 volume figures using separate columns for both counterparties’ opening or closing status. Add a second hypothetical day with high transfer volume but no net change in open interest. Explain why neither day’s count alone establishes a directional forecast. Prepare fields for contract month, observation date, release time and data revision status. Finish with a paper research question that uses open interest only after publication and tests its incremental value against a price-only baseline. A defensible study preserves the accounting and timing rather than equating outstanding contracts with a one-sided flow of conviction.
Can you apply the idea?
Answer three questions, then check the explanation for every answer. You can repeat the check after reviewing the lesson.
Knowledge check: not attempted
Make this lesson part of your process.
Finish the reading and its practice task, then mark the lesson as completed.
0 of 100 lessons completed
Gold Trading Mastery
From gold market fundamentals to technical analysis, execution, quantitative research and AI. A structured 160-chapter course.
Explore the book →Continue the beginner course
What Is XAU/USD? Gold Trading Explained for Beginners →
How to Read Gold Candlestick Charts: A Beginner’s Guide →
Market, Limit and Stop Orders in Gold Trading →
Gold Trading Costs: Spread, Slippage and Financing →
Stop-Loss and Take-Profit in Gold: Beginner Essentials →
Your First Gold Trading Plan: Practise Before Going Live →
Gold Position Sizing: Calculate Exposure Before You Trade →
Gold Leverage and Margin: Understand the Difference →
Support and Resistance in Gold: Read Zones Without Guessing →
Gold and the Economic Calendar: CPI, Jobs and the Fed →
Multiple-Timeframe Gold Analysis: Context, Setup and Trigger →
Gold Trading Expectancy: Evaluate Results Beyond Win Rate →
Gold Trends and Ranges: Identify the Market Before the Setup →
Gold ATR for Beginners: Measure Movement, Not Direction →
Gold Breakouts and Failed Breaks: Define the Evidence →
Gold Trading Drawdown: Understand Losses and Recovery →
How to Backtest a Gold Trading Rule Without Hindsight →
The Gold Pre-Trade Checklist: Turn a Plan into a Decision →
Gold Liquidity and Trading Sessions: Study the Conditions →
Audit a Gold Trade: Quotes, Triggers and Actual Fills →
Multiple Gold Positions: Measure the Combined Exposure →
Partial Exits and Breakeven Stops: Follow the Arithmetic →
Small Samples in Gold Trading: Describe the Uncertainty →
Your Gold Trading Review: Version the Rule Before Testing Again →
Gold Weight and Purity: Calculate the Fine Gold Content →
Gold Premiums and Buyback: Calculate the Round-Trip Hurdle →
Allocated and Unallocated Gold: Understand the Ownership Claim →
Gold Benchmarks and Spot Quotes: Compare Like with Like →
Gold Returns in Your Currency: Separate Metal and FX Effects →
Gold Futures Tick Value: Translate Price Moves into Money →
Gold Futures Daily Settlement: Follow the Cash Through the Account →
Gold COT Reports: Read Positioning Without Inventing a Signal →
Gold ETFs: NAV, Market Price and Tracking Difference →
Gold in a Portfolio: Calculate Weight Drift and Rebalancing →
Gold Moving Averages: Read Smoothing Without Predicting the Future →
Gold RSI: Momentum Is Not a Reversal Promise →
Gold Volume: Distinguish Ticks, Contracts and Coverage →
Gold Heikin Ashi Charts: Separate Display Prices from Fills →
Gold Indicator Repainting: Distinguish Live Signals from Confirmed History →
Gold Backtests: When One Candle Touches Both Stop and Target →
Gold TradingView Alerts: Audit the Saved Script Snapshot →
Gold Signal Webhooks: Verify Delivery, Freshness and Duplicates →
Gold Trading Returns: Add Money, Compound Percentages →
Gold Account Performance: Separate Deposits from Trading Gains →
Gold Realized Volatility: Calculate the Statistic and Audit Its Assumptions →
Gold Correlation: Align Returns Before Interpreting the Relationship →
Gold Event Studies: Measure the Reaction Without Inventing the Cause →
Gold Strategy Robustness: Count the Experiments Behind the Winner →
Gold Stress Tests: Model Gaps, Liquidity and Tail Losses Together →
Gold Options at Expiry: Separate Payoff, Premium and Exercise →
Gold Option Delta and Gamma: Estimate Exposure Without Freezing It →
Gold Implied Volatility: Separate the Price of Uncertainty from Direction →
Gold Futures Rolls: Reconcile Contract P&L with a Continuous Chart →
Gold Mining Shares: Understand the Business Behind the Metal Exposure →
Gold VWAP: Define the Anchor, Price Input and Volume →
Gold Bollinger Bands: Distinguish Price Dispersion from a Reversal Signal →
Gold MACD: Read the Line, Signal and Histogram as Different Comparisons →
Gold Donchian Channels: Use the Prior Window Without Circular Signals →
Gold Fibonacci Retracements: Audit the Anchors Before Trusting the Level →
Gold Position Accounting: Distinguish Net Exposure from Gross Tickets →
Gold Bracket Orders: Audit Partial Fills and Cancellation States →
Gold Trade Excursions: Measure MAE and MFE Without Rewriting the Past →
Gold Execution Shortfall: Reconcile Decisions, Fills and Unfilled Quantity →
Gold Strategy Monitoring: Separate Data Failures, Execution Drift and Method Decay →
Gold Order Books: Translate Displayed Depth into a Conditional Fill Estimate →
Gold Calendar Spreads: Calculate Relative-Maturity P&L and Leg Risk →
Gold Basis Risk: Explain Why a Futures Hedge Can Leave a Residual Loss →
Gold Lending and Lease Rates: Separate Metal Interest from Price Exposure →
Gold Assay and Authenticity: Separate a Purity Calculation from Evidence →
Gold Storage and Insurance: Reconcile the Inventory and the Protection →
Gold Inventory Hedging: Match Fine Ounces and Finance the Cash Path →
Gold and Currency Hedging: Separate Metal Exposure from the Conversion Leg →
Gold Capstone: Build One Report from Price, Basis, Costs and Liquidity →
Gold Profit Factor: Reconcile the Winning and Losing Dollars →
Gold Sharpe Ratios: Align Excess Returns, Frequency and Risk →
Gold Sortino Ratios: Define the Target and the Downside Denominator →
Gold Win Rates: Calculate a Confidence Interval and State Its Assumptions →
Gold Return Dependence: Keep the Sequence When Measuring Risk →
Gold Bootstrap Studies: Resample the Evidence Without Inventing New Markets →
Gold Walk-Forward Tests: Freeze Each Rule Before Its Next Evaluation →
Gold Research Universes: Keep Delisted Products and Historical Eligibility Visible →
Gold Performance Attribution: Separate Within-Condition Results from the Opportunity Mix →
Gold Performance Capstone: Audit a Claim from Signal Ledger to Account Equity →
Build a Gold Trading System: Write the Operating Charter Before the Signal →
Gold Setup Rules: Translate Chart Language into Testable Predicates →
Gold System States: Separate Eligibility, Submission, Exposure and Rearming →
Gold System Sizing: Reserve Risk and Check Whether a Trade Is Feasible →
Gold System Exits: Define Priority, Timeouts and Conflicting Events →
Release a Gold Paper System: Test the Runbook Before Increasing Exposure →
Gold Execution Hesitation: Distinguish a Missed Entry from a New Decision →
Gold Overtrading: Audit Eligibility Before Counting Activity →
Gold Losing Streaks: Prevent Recovery Pressure from Rewriting Risk →
Gold Rule Changes: Separate Emergency Repairs from Strategy Redesign →
Gold Trading Journals: Score Decision Quality Separately from Profit →
Gold Case Study: Audit a Trend-Continuation Trade from Context to Net Exit →
Gold Case Study: Accept a Failed Range Break Without Moving the Evidence →
Gold Case Study: Document a Valid No-Trade Decision Around a Scheduled Event →
Gold Case Study: Recover from a Lost Order Response Without Duplicating Exposure →
Gold Lesson 100: Complete the Paper-System Project and Defend Its Evidence →
Market Desk and position-risk calculator →
Position sizing explained → · Build a trading journal →
Lesson sources and further study
CME Group: Open-interest reporting conventions
Core course references
CME Group: Gold Product Overview. Investor.gov: Types of Orders explains order concepts for stocks; check the execution rules of your specific gold instrument.
Gabriel Nicolaev — CyGuru · Published 7 November 2026. Educational material. Illustrative prices are not current quotes or trade recommendations.