Gold Option Delta and Gamma: Estimate Exposure Without Freezing It
Translate option delta into a local gold-price sensitivity, calculate a gamma adjustment and explain why the approximation changes.
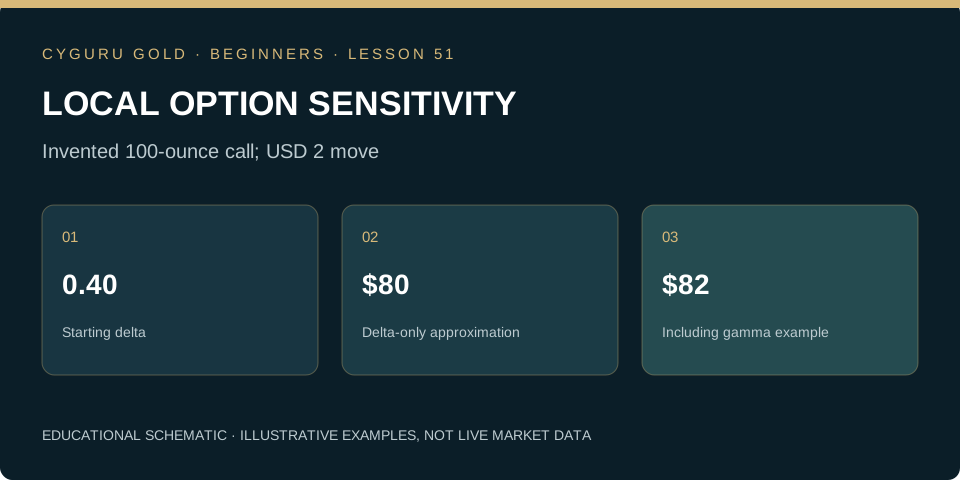
Delta is a local sensitivity, not a fixed position
For an option priced per ounce, delta estimates the change in its quoted premium for a small one-dollar move in the referenced underlying, holding other modeled inputs constant. A call delta is generally positive and a put delta generally negative for a purchased vanilla option. Multiply by the contract’s ounce multiplier and the number of contracts to translate that sensitivity into dollars. State which underlying is referenced: a futures-option delta applies to its underlying futures price, not automatically to another broker’s spot series. Delta describes a neighborhood around the current state, not the entire future payoff.
Calculate a small-move approximation
Imagine one purchased gold call with a 100-ounce multiplier and delta 0.40. Its initial directional sensitivity is approximately 40 ounce-equivalents. For a USD 2-per-ounce rise in the underlying futures, a delta-only estimate is 0.40 × 2 × 100 = USD 80 of option-value increase. For two identical contracts the estimate is USD 160. These calculations hold time, volatility and other inputs fixed. They are not the premium cost, margin requirement or maximum possible loss. Preserve the quote units so a per-ounce delta is not accidentally multiplied by 100 twice.
Use gamma to describe changing delta
Gamma is the rate at which delta changes with the underlying price under the model’s convention. Assume illustrative gamma of 0.01 per one-dollar underlying move. For a positive USD 2 move, a local second-order premium estimate is delta × change plus one-half × gamma × change squared. That equals 0.80 + 0.02 = USD 0.82 per ounce, or USD 82 for the 100-ounce contract. A first-order estimate of the new delta would be 0.42. These are local approximations using starting sensitivities; large moves or changing conditions require repricing instead of stretching the formula beyond its useful neighborhood.
| Underlying move | Delta contribution / oz | Gamma contribution / oz | 100-ounce result |
|---|---|---|---|
| +$2 | +$0.80 | +$0.02 | +$82 |
| −$2 | −$0.80 | +$0.02 | −$78 |
| Initial directional exposure | 0.40 × 100 oz | 40 ounce-equivalents |
Include the sensitivities the directional estimate omitted
Time passing, implied volatility changing and the underlying moving together can produce a result unlike the delta-only estimate. Theta concerns time sensitivity, while vega concerns volatility sensitivity; their exact quoted units must be checked. Greeks come from a pricing model and market inputs rather than a contractual promise about the next quote. Near expiry, sensitivity can change sharply around a strike. A paper portfolio should therefore be evaluated across multiple underlying, time and volatility scenarios, with actual executable spreads considered separately from theoretical marks.
Recognize the limits of a delta-neutral label
Suppose the one-call position has an initial delta equivalent of +40 ounces, and an idealized short linear exposure of 40 ounces offsets it. Initial net delta is approximately zero, before basis differences and costs. Gamma remains; the option’s delta changes when price moves while the linear exposure’s unit sensitivity does not. Time and volatility sensitivities also remain. Rebalancing the hedge creates transactions, costs and operational demands. Delta neutrality at one instant therefore does not mean no risk, guaranteed profit or a hedge that can be left untouched regardless of price movement.
Practice task: write a sensitivity memo
Reproduce the USD 80 delta-only and USD 82 delta-plus-gamma examples. Repeat for a negative USD 2 move using the same starting values: the second-order estimate is −0.80 + 0.02 = −0.78 per ounce, or −USD 78. Explain why the two approximate outcomes are not symmetric for a long option with positive gamma. State the assumptions and identify two unmodeled changes that could overwhelm the small difference. Finally, describe why delta should not be presented as the verified probability of your trade making money, even when practitioners use related probability interpretations under particular models.
Can you apply the idea?
Answer three questions, then check the explanation for every answer. You can repeat the check after reviewing the lesson.
Knowledge check: not attempted
Make this lesson part of your process.
Finish the reading and its practice task, then mark the lesson as completed.
0 of 54 lessons completed
Gold Trading Mastery
From gold market fundamentals to technical analysis, execution, quantitative research and AI. A structured 160-chapter course.
Explore the book →Continue the beginner course
What Is XAU/USD? Gold Trading Explained for Beginners →
How to Read Gold Candlestick Charts: A Beginner’s Guide →
Market, Limit and Stop Orders in Gold Trading →
Gold Trading Costs: Spread, Slippage and Financing →
Stop-Loss and Take-Profit in Gold: Beginner Essentials →
Your First Gold Trading Plan: Practise Before Going Live →
Gold Position Sizing: Calculate Exposure Before You Trade →
Gold Leverage and Margin: Understand the Difference →
Support and Resistance in Gold: Read Zones Without Guessing →
Gold and the Economic Calendar: CPI, Jobs and the Fed →
Multiple-Timeframe Gold Analysis: Context, Setup and Trigger →
Gold Trading Expectancy: Evaluate Results Beyond Win Rate →
Gold Trends and Ranges: Identify the Market Before the Setup →
Gold ATR for Beginners: Measure Movement, Not Direction →
Gold Breakouts and Failed Breaks: Define the Evidence →
Gold Trading Drawdown: Understand Losses and Recovery →
How to Backtest a Gold Trading Rule Without Hindsight →
The Gold Pre-Trade Checklist: Turn a Plan into a Decision →
Gold Liquidity and Trading Sessions: Study the Conditions →
Audit a Gold Trade: Quotes, Triggers and Actual Fills →
Multiple Gold Positions: Measure the Combined Exposure →
Partial Exits and Breakeven Stops: Follow the Arithmetic →
Small Samples in Gold Trading: Describe the Uncertainty →
Your Gold Trading Review: Version the Rule Before Testing Again →
Gold Weight and Purity: Calculate the Fine Gold Content →
Gold Premiums and Buyback: Calculate the Round-Trip Hurdle →
Allocated and Unallocated Gold: Understand the Ownership Claim →
Gold Benchmarks and Spot Quotes: Compare Like with Like →
Gold Returns in Your Currency: Separate Metal and FX Effects →
Gold Futures Tick Value: Translate Price Moves into Money →
Gold Futures Daily Settlement: Follow the Cash Through the Account →
Gold COT Reports: Read Positioning Without Inventing a Signal →
Gold ETFs: NAV, Market Price and Tracking Difference →
Gold in a Portfolio: Calculate Weight Drift and Rebalancing →
Gold Moving Averages: Read Smoothing Without Predicting the Future →
Gold RSI: Momentum Is Not a Reversal Promise →
Gold Volume: Distinguish Ticks, Contracts and Coverage →
Gold Heikin Ashi Charts: Separate Display Prices from Fills →
Gold Indicator Repainting: Distinguish Live Signals from Confirmed History →
Gold Backtests: When One Candle Touches Both Stop and Target →
Gold TradingView Alerts: Audit the Saved Script Snapshot →
Gold Signal Webhooks: Verify Delivery, Freshness and Duplicates →
Gold Trading Returns: Add Money, Compound Percentages →
Gold Account Performance: Separate Deposits from Trading Gains →
Gold Realized Volatility: Calculate the Statistic and Audit Its Assumptions →
Gold Correlation: Align Returns Before Interpreting the Relationship →
Gold Event Studies: Measure the Reaction Without Inventing the Cause →
Gold Strategy Robustness: Count the Experiments Behind the Winner →
Gold Stress Tests: Model Gaps, Liquidity and Tail Losses Together →
Gold Options at Expiry: Separate Payoff, Premium and Exercise →
Gold Implied Volatility: Separate the Price of Uncertainty from Direction →
Gold Futures Rolls: Reconcile Contract P&L with a Continuous Chart →
Gold Mining Shares: Understand the Business Behind the Metal Exposure →
Market Desk and position-risk calculator →
Position sizing explained → · Build a trading journal →
Lesson sources and further study
CME Group: Greeks and implied volatility data conventions
OCC Options Industry Council: Delta and changing sensitivities
Core course references
CME Group: Gold Product Overview. Investor.gov: Types of Orders explains order concepts for stocks; check the execution rules of your specific gold instrument.
Gabriel Nicolaev — CyGuru · Published 6 November 2026. Educational material. Illustrative prices are not current quotes or trade recommendations.