Gold Inventory Hedging: Match Fine Ounces and Finance the Cash Path
Size a hypothetical inventory hedge, calculate rounding residuals and distinguish matched price exposure from collateral and sale-timing risk.
Start with the inventory objective rather than a price opinion
An inventory holder may seek to reduce exposure between acquiring metal and selling it to a customer. That objective differs from predicting whether gold rises. Define which quantity is owned or contractually committed, its fine-metal content, expected sale date and pricing formula. A hedge against uncommitted future inventory can instead create a speculative exposure if the purchase never happens. Keep confirmed holdings, expected receipts and customer orders in separate categories. Hedging should follow the business obligation being managed, not become a reason to accumulate an unrelated trading position.
Translate fine weight into the hedge unit
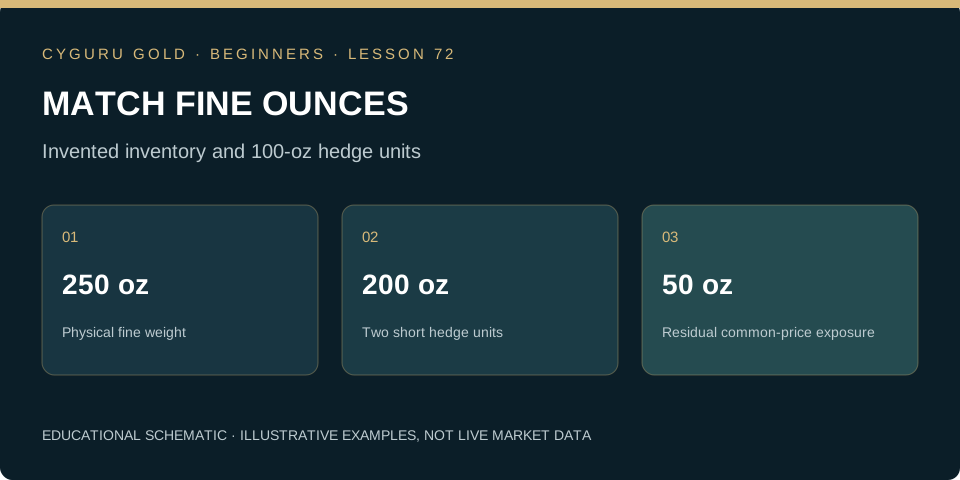
Assume a fictional inventory of 250 fine troy ounces and a hypothetical futures multiplier of 100 ounces per contract. A full ounce-for-ounce offset would require 2.5 contracts, which may not be tradable in that contract’s whole-unit system. Shorting two leaves 50 ounces of net long quantity; shorting three creates 50 ounces net short. Different smaller instruments could change the rounding choices if their specifications, costs and availability were verified. The arithmetic does not select the appropriate policy. State the permitted residual and its dollar sensitivity rather than describing the nearest ticket count as a perfect hedge.
Calculate the quantity residual under a common move
For the two-contract short hedge, let the physical reference and futures both fall USD 40 per ounce over aligned timestamps, with no basis change. The 250-ounce inventory loses USD 10,000 in marked value. The 200-ounce futures short gains USD 8,000 before costs. Combined residual is −USD 2,000, matching the unhedged 50 ounces multiplied by −40. This result isolates hedge rounding. If physical and futures move differently, add basis effects separately, using the sign convention from lesson 68. Fees, physical premiums and financing add further components. Do not label every imperfect offset as the same source of risk.
| Component | Quantity | P&L on common −$40 move |
|---|---|---|
| Physical fine inventory | +250 oz | −$10,000 |
| Two short hedge units | −200 oz | +$8,000 |
| Residual common-price exposure | +50 oz | −$2,000 |
| Three-unit alternative | −50 oz net | Different rounding policy |
Follow customer pricing and exposure-release timing
If a customer fixes the gold price before delivery, the inventory’s economic exposure can change when that binding price commitment is made rather than when metal physically leaves the vault. Conversely, an indicative quote that expires or remains nonbinding may not eliminate the risk. Record the commercial terms and avoid assuming that every order form creates an equivalent obligation. The futures hedge should be adjusted according to the documented exposure policy and actual fills. Closing it too early or leaving it after the inventory price is fixed can create an unintended directional interval. Map the timestamps instead of relying only on end-of-day balances.
Plan for a rising-price collateral call
When gold rises, a short futures hedge can require cash while the physical inventory gains marked value. The asset gain may not be available as cash before the margin deadline. A business that is approximately hedged economically can still face a funding problem. Stress the accessible cash, collateral eligibility, transfer delay and broker requirements together. Do not assume the future customer payment will arrive exactly when needed. A decision to hold fewer hedge contracts might reduce collateral demands while increasing market exposure; that tradeoff requires an explicit policy. No numerical hedge ratio removes the need to finance the path.
Practice task: submit an inventory exposure ledger
Prepare a record for 250 fine ounces, two hypothetical 100-ounce short contracts and 50 residual long ounces. Reproduce the −USD 2,000 common-move residual. Add a separate scenario where the futures short loses cash before the customer pays, and name the funding source without inventing a provider’s margin rules. Include an event where a customer price becomes fixed and explain when the hedge quantity should be reviewed. Your final memo should separate quantity mismatch, basis risk, collateral timing and contract cancellation risk. A hedge is accountable when its remaining exposures can be named, measured and funded.
Can you apply the idea?
Answer three questions, then check the explanation for every answer. You can repeat the check after reviewing the lesson.
Knowledge check: not attempted
Make this lesson part of your process.
Finish the reading and its practice task, then mark the lesson as completed.
0 of 100 lessons completed
Gold Trading Mastery
From gold market fundamentals to technical analysis, execution, quantitative research and AI. A structured 160-chapter course.
Explore the book →Continue the beginner course
What Is XAU/USD? Gold Trading Explained for Beginners →
How to Read Gold Candlestick Charts: A Beginner’s Guide →
Market, Limit and Stop Orders in Gold Trading →
Gold Trading Costs: Spread, Slippage and Financing →
Stop-Loss and Take-Profit in Gold: Beginner Essentials →
Your First Gold Trading Plan: Practise Before Going Live →
Gold Position Sizing: Calculate Exposure Before You Trade →
Gold Leverage and Margin: Understand the Difference →
Support and Resistance in Gold: Read Zones Without Guessing →
Gold and the Economic Calendar: CPI, Jobs and the Fed →
Multiple-Timeframe Gold Analysis: Context, Setup and Trigger →
Gold Trading Expectancy: Evaluate Results Beyond Win Rate →
Gold Trends and Ranges: Identify the Market Before the Setup →
Gold ATR for Beginners: Measure Movement, Not Direction →
Gold Breakouts and Failed Breaks: Define the Evidence →
Gold Trading Drawdown: Understand Losses and Recovery →
How to Backtest a Gold Trading Rule Without Hindsight →
The Gold Pre-Trade Checklist: Turn a Plan into a Decision →
Gold Liquidity and Trading Sessions: Study the Conditions →
Audit a Gold Trade: Quotes, Triggers and Actual Fills →
Multiple Gold Positions: Measure the Combined Exposure →
Partial Exits and Breakeven Stops: Follow the Arithmetic →
Small Samples in Gold Trading: Describe the Uncertainty →
Your Gold Trading Review: Version the Rule Before Testing Again →
Gold Weight and Purity: Calculate the Fine Gold Content →
Gold Premiums and Buyback: Calculate the Round-Trip Hurdle →
Allocated and Unallocated Gold: Understand the Ownership Claim →
Gold Benchmarks and Spot Quotes: Compare Like with Like →
Gold Returns in Your Currency: Separate Metal and FX Effects →
Gold Futures Tick Value: Translate Price Moves into Money →
Gold Futures Daily Settlement: Follow the Cash Through the Account →
Gold COT Reports: Read Positioning Without Inventing a Signal →
Gold ETFs: NAV, Market Price and Tracking Difference →
Gold in a Portfolio: Calculate Weight Drift and Rebalancing →
Gold Moving Averages: Read Smoothing Without Predicting the Future →
Gold RSI: Momentum Is Not a Reversal Promise →
Gold Volume: Distinguish Ticks, Contracts and Coverage →
Gold Heikin Ashi Charts: Separate Display Prices from Fills →
Gold Indicator Repainting: Distinguish Live Signals from Confirmed History →
Gold Backtests: When One Candle Touches Both Stop and Target →
Gold TradingView Alerts: Audit the Saved Script Snapshot →
Gold Signal Webhooks: Verify Delivery, Freshness and Duplicates →
Gold Trading Returns: Add Money, Compound Percentages →
Gold Account Performance: Separate Deposits from Trading Gains →
Gold Realized Volatility: Calculate the Statistic and Audit Its Assumptions →
Gold Correlation: Align Returns Before Interpreting the Relationship →
Gold Event Studies: Measure the Reaction Without Inventing the Cause →
Gold Strategy Robustness: Count the Experiments Behind the Winner →
Gold Stress Tests: Model Gaps, Liquidity and Tail Losses Together →
Gold Options at Expiry: Separate Payoff, Premium and Exercise →
Gold Option Delta and Gamma: Estimate Exposure Without Freezing It →
Gold Implied Volatility: Separate the Price of Uncertainty from Direction →
Gold Futures Rolls: Reconcile Contract P&L with a Continuous Chart →
Gold Mining Shares: Understand the Business Behind the Metal Exposure →
Gold VWAP: Define the Anchor, Price Input and Volume →
Gold Bollinger Bands: Distinguish Price Dispersion from a Reversal Signal →
Gold MACD: Read the Line, Signal and Histogram as Different Comparisons →
Gold Donchian Channels: Use the Prior Window Without Circular Signals →
Gold Fibonacci Retracements: Audit the Anchors Before Trusting the Level →
Gold Position Accounting: Distinguish Net Exposure from Gross Tickets →
Gold Bracket Orders: Audit Partial Fills and Cancellation States →
Gold Trade Excursions: Measure MAE and MFE Without Rewriting the Past →
Gold Execution Shortfall: Reconcile Decisions, Fills and Unfilled Quantity →
Gold Strategy Monitoring: Separate Data Failures, Execution Drift and Method Decay →
Gold Open Interest: Follow the Contract Ledger Before Reading Sentiment →
Gold Order Books: Translate Displayed Depth into a Conditional Fill Estimate →
Gold Calendar Spreads: Calculate Relative-Maturity P&L and Leg Risk →
Gold Basis Risk: Explain Why a Futures Hedge Can Leave a Residual Loss →
Gold Lending and Lease Rates: Separate Metal Interest from Price Exposure →
Gold Assay and Authenticity: Separate a Purity Calculation from Evidence →
Gold Storage and Insurance: Reconcile the Inventory and the Protection →
Gold and Currency Hedging: Separate Metal Exposure from the Conversion Leg →
Gold Capstone: Build One Report from Price, Basis, Costs and Liquidity →
Gold Profit Factor: Reconcile the Winning and Losing Dollars →
Gold Sharpe Ratios: Align Excess Returns, Frequency and Risk →
Gold Sortino Ratios: Define the Target and the Downside Denominator →
Gold Win Rates: Calculate a Confidence Interval and State Its Assumptions →
Gold Return Dependence: Keep the Sequence When Measuring Risk →
Gold Bootstrap Studies: Resample the Evidence Without Inventing New Markets →
Gold Walk-Forward Tests: Freeze Each Rule Before Its Next Evaluation →
Gold Research Universes: Keep Delisted Products and Historical Eligibility Visible →
Gold Performance Attribution: Separate Within-Condition Results from the Opportunity Mix →
Gold Performance Capstone: Audit a Claim from Signal Ledger to Account Equity →
Build a Gold Trading System: Write the Operating Charter Before the Signal →
Gold Setup Rules: Translate Chart Language into Testable Predicates →
Gold System States: Separate Eligibility, Submission, Exposure and Rearming →
Gold System Sizing: Reserve Risk and Check Whether a Trade Is Feasible →
Gold System Exits: Define Priority, Timeouts and Conflicting Events →
Release a Gold Paper System: Test the Runbook Before Increasing Exposure →
Gold Execution Hesitation: Distinguish a Missed Entry from a New Decision →
Gold Overtrading: Audit Eligibility Before Counting Activity →
Gold Losing Streaks: Prevent Recovery Pressure from Rewriting Risk →
Gold Rule Changes: Separate Emergency Repairs from Strategy Redesign →
Gold Trading Journals: Score Decision Quality Separately from Profit →
Gold Case Study: Audit a Trend-Continuation Trade from Context to Net Exit →
Gold Case Study: Accept a Failed Range Break Without Moving the Evidence →
Gold Case Study: Document a Valid No-Trade Decision Around a Scheduled Event →
Gold Case Study: Recover from a Lost Order Response Without Duplicating Exposure →
Gold Lesson 100: Complete the Paper-System Project and Defend Its Evidence →
Market Desk and position-risk calculator →
Position sizing explained → · Build a trading journal →
Lesson sources and further study
CME Group: Physical price exposure and futures hedges
Core course references
CME Group: Gold Product Overview. Investor.gov: Types of Orders explains order concepts for stocks; check the execution rules of your specific gold instrument.
Gabriel Nicolaev — CyGuru · Published 7 November 2026. Educational material. Illustrative prices are not current quotes or trade recommendations.